Airtel: Recharge, Bank & Loans

Screenshots
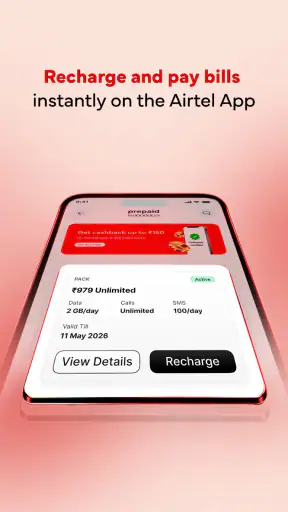
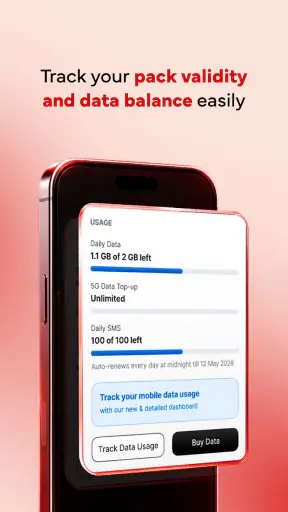
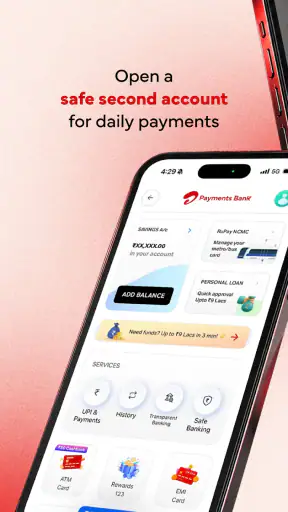
Details
- Rating
- 8.78K reviews
- Version
- 4.149.2
- Developer
- Airtel
Analysis by Norviv
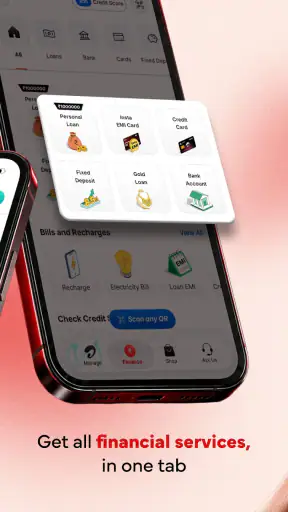
I usually judge a finance app by a simple question: does it make routine money tasks easier without making me think about the app itself? Airtel: Recharge, Bank & Loans is built around that idea. It brings mobile recharges, bill payments, UPI payments, rewards, banking-related services, and loan access into one place, so it is aimed less at people who want a specialist budgeting tool and more at people who want a practical daily money hub.
After spending time with it, I see the appeal clearly. If you already use Airtel for mobile service, the app can reduce the number of separate tools you need for everyday transactions. The trade-off is that its broad scope can feel busier than a focused payment app, and the best experience depends on which of its services you actually need. My recommendation therefore comes down to your habits: it is a strong convenience app for Airtel customers and people who regularly use several supported payment services, but it is not automatically the best choice for someone seeking detailed financial planning or a minimalist wallet.
What I looked for before recommending it
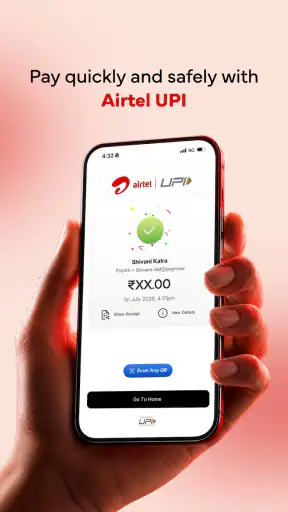
For a finance app like this, I pay attention to four things before anything else. The first is routine usefulness: can I complete a recharge or bill payment quickly, without navigating through screens that feel unrelated? The second is payment clarity: are the amount, recipient, and final action easy to understand before I confirm? The third is coverage of everyday needs, because combining services is only helpful when the combination reflects real life rather than simply adding more buttons. The fourth is trust and control. Money apps need clear transaction histories, sensible confirmation steps, and enough information for me to know what happened after a payment.
Airtel: Recharge, Bank & Loans is a free finance app from Airtel, with an Everyone content rating. It has been available since July 7, 2016, and its current version is 4.149.2. Those details matter less than the way the app fits into a person’s routine, but they do show that this is an established product rather than a newly launched experiment.
The scale of its audience is also substantial: it has passed 500 million installs, with an average rating of 4.0 from around 7.9 million ratings. I would not treat a large install count or rating as a substitute for personal testing, but they do suggest that the app serves a broad range of users and has had plenty of opportunity to refine common workflows. The app also shows around 8.8 thousand written reviews, which can be useful when checking whether a particular issue is common, although individual payment experiences can vary.
The minimum operating-system requirement is Android 7.0, making it accessible to many older Android phones. That is helpful for users who do not upgrade devices often. At the same time, an older phone may make a multi-purpose finance app feel slower or more crowded than it would on a newer device, so I would keep the app updated and leave enough storage available for normal operation.
How the all-in-one approach works in daily life
The strongest reason to use this app is concentration. Instead of opening one app for a mobile recharge, another for a bill, and another for a UPI payment, I can start with Airtel and see whether the task belongs there. That does not guarantee that every transaction will be the fastest possible route, but it reduces the mental overhead of remembering which service handles which job.
Stories Picked for You
Life360 Works Better When Your Household Agrees on What to Share
YouVersion Bible Fits Scripture into Everyday Phone Routines
Matchington Mansion Review: Match-Three Puzzles With a Place to Restore
Android Auto Shows Why Safer Driving Software Does Less
Google Find Hub Runs on Shared Devices and Quiet Trust
Sygic GPS Navigation: The Ultimate Offline Travel Companion
A realistic example is a busy evening when my phone plan needs a recharge, an electricity bill is due, and I need to send money to a family member. In a specialist-only setup, I might move between several apps and repeatedly check whether the payment went through. With Airtel: Recharge, Bank & Loans, I can begin with the mobile-related task and continue through the other available payment tools without changing my general starting point. I still check each confirmation carefully, but the workflow feels more organized.
That convenience is especially useful for households where one person handles several recurring payments. The app can act as a central place to review what needs attention, rather than relying on scattered reminders. I would still keep a separate note or calendar for due dates, because a payment app is not necessarily a full household budgeting system. The practical insight is to use Airtel as the transaction desk, not as the only record of your financial life.
Where the app wins against separate specialist tools
The app’s main advantage is reduced switching between everyday money tasks. A dedicated recharge app may offer a cleaner single-purpose path, while a dedicated UPI app may feel more focused for transfers. Airtel’s value appears when I need several related actions in one session. The broader menu becomes an advantage rather than a distraction when I am already paying a bill, checking a reward, or handling a recharge.
Its Airtel connection is another practical strength. For someone who uses Airtel mobile services, having recharge activity close to payment and account-related tools can make the experience feel more coherent. I do not have to treat the mobile account as a separate world from the rest of my routine payments. That is a small convenience, but repeated small conveniences are exactly what make a finance app worth keeping.
The rewards area can also influence how often I return. I would not choose a financial app solely because it displays rewards, and I would always read the conditions attached to any offer before changing how I pay. Still, rewards can make the central app more useful for people who already prefer it for recharges and bills. The sensible approach is to treat them as an occasional benefit, not as guaranteed savings.
The inclusion of banking and loans broadens the app beyond simple payments. This may be useful when I want to explore more financial services without installing another app immediately. However, the presence of a loan section should not be mistaken for a recommendation to borrow. I would compare the total repayment obligation, eligibility terms, and consequences of missed payments before accepting any credit product. Convenience at the application stage should never replace careful financial judgment.
Small habits that make the experience safer and less frustrating
One useful habit is to pause at the final confirmation screen rather than tapping through automatically. I check the mobile number, biller or recipient, and amount every time. This is particularly important when I am paying from a list of saved or recently used contacts, because familiarity can make an incorrect selection feel trustworthy.
A second habit is to separate successful payment from successful completion of the underlying service. After a recharge or bill payment, I look for the app’s confirmation and then, where practical, check that the balance, plan, or bill status has actually updated. A delayed update does not necessarily mean the payment failed, so repeating the transaction immediately can create a duplicate charge. I prefer to wait for a clear status before trying again and keep the transaction reference available if support is needed.
A third insight is to avoid turning rewards into a spending trigger. If I would not make a payment without the reward, the reward should not be the reason to make it. I compare the final value with the normal payment route and read any conditions displayed in the offer. This keeps the rewards feature in its proper role: a possible extra, not the foundation of my financial decisions.
For loans, I use an even stricter workflow. I first decide whether borrowing is necessary, then compare the total cost and repayment schedule with alternatives. I do not enter a loan application simply because it is conveniently placed beside recharges. The app can make access easier, but the responsibility for affordability remains with me.
What may feel less convenient
The same breadth that makes Airtel useful can make it feel busy. If I only want to send a quick UPI payment, a specialist payment app may present fewer distractions. A user who rarely recharges an Airtel number or uses the app’s other services may see the extra sections as clutter rather than value. In that situation, the all-in-one design does not automatically beat a simpler alternative.
I also would not choose it as my primary tool for detailed spending analysis. The app is centered on transactions and financial services, not on replacing a dedicated budgeting method. Someone who wants category-based expense planning, long-term savings goals, investment research, or a complete household ledger may need another solution alongside it. Airtel can be part of that setup, but it should not be expected to cover every financial task.
Another point is that payment convenience can encourage overreliance on one ecosystem. I like having a central app, but I still keep basic records outside it and maintain access to alternative payment methods. If an app is unavailable, a transaction is delayed, or a service does not fit the available workflow, I do not want my entire routine to stop. This is not a criticism unique to Airtel; it is a sensible precaution with any single finance app.
When another category of app is a better fit
If your priority is the cleanest possible UPI transfer experience, a focused UPI app may suit you better. It may place the payment action front and center, which can be preferable when you make transfers frequently and rarely need recharges, rewards, or loan-related services. I would choose that route for a person who values a narrow, uncluttered workflow above consolidation.
If your priority is mobile service management, a carrier-focused app can be the better choice when it gives you exactly the account controls you use most. Airtel’s broader finance direction is useful when payments matter alongside the mobile account. But if you only need to manage a plan and nothing else, a wider finance hub may be more than you need.
If your priority is financial planning, I would look toward a budgeting or money-management tool as the main companion. Airtel is more suitable for acting on a payment than for building a complete picture of spending over time. I would pair it with a simple spreadsheet, banking records, or a dedicated planning app rather than expecting the transaction hub to provide every insight.
If your priority is borrowing, comparison matters even more. I would not select a loan simply because it appears inside an app I already trust for recharges. I would compare providers, read the full terms, and calculate affordability independently. Airtel may be a convenient starting point for exploring an option, but it should not be the only place I evaluate credit.
The real cost of changing your payment routine
Switching to Airtel is relatively easy if your main goal is to centralize recharges, bills, UPI, and related services. The app is free, and the Everyone rating makes it suitable for a broad audience. The larger cost is not money; it is habit. I need to learn where each function sits, decide which notifications are useful, and develop a reliable way to confirm transactions.
There is also a record-keeping cost when moving between apps. Previous payment histories may remain distributed across the services I used before, so I would not uninstall every alternative immediately. I would keep older apps or records available until recurring payments, saved details, and important references are comfortably organized in the new routine.
For an Airtel customer, the switch may feel natural because the app connects a familiar mobile relationship with broader financial tasks. For someone outside that pattern, the benefit depends on whether the app’s extra services genuinely replace other tools. My advice is to start with one repeated task, such as a monthly recharge or bill, and assess how clear the confirmation and history feel before moving everything over.
I would also review notification settings after installation. Finance alerts can be valuable, but too many promotional or reward messages can make important transaction notices harder to spot. Keeping essential payment notifications while reducing distractions creates a better balance. This small adjustment is easy to overlook, yet it has a direct effect on whether the app feels helpful or noisy.
My recommendation for different users
I recommend Airtel: Recharge, Bank & Loans to people who want one practical starting point for mobile recharges, UPI, bills, rewards, and additional financial services. It is particularly convincing when you already use Airtel and regularly handle several everyday payments. In that context, the app’s breadth saves time and reduces the need to remember multiple separate destinations.
I would be more selective for someone who only wants the fastest possible transfer screen, someone who dislikes multi-service interfaces, or someone searching for serious budgeting and financial analysis. Those users may be happier with a focused payment tool or a dedicated planning app, using Airtel only when its mobile and bill features are directly useful.
My final view is positive but practical: this is a capable convenience hub, not a complete replacement for every financial tool. Start with routine transactions, verify each confirmation, treat rewards as optional, and approach the loan section with independent scrutiny. If that matches the way you manage money, Airtel can earn a permanent place on your phone. If you want one narrow function with no surrounding services, a specialist alternative will probably feel cleaner.
For me, the deciding factor is not the number of features on the screen. It is whether those features remove friction from tasks I already perform. When they do, Airtel: Recharge, Bank & Loans is genuinely useful. When they do not, its broad design becomes unnecessary weight. That makes it worth trying for convenience-focused users, while leaving room for a more specialized choice when precision and simplicity matter more.
Frequently Asked Questions
01What is Airtel: Recharge, Bank & Loans used for?
Airtel: Recharge, Bank & Loans is a multifunctional financial and telecom app designed for Airtel customers. From the app, you can recharge prepaid numbers, pay mobile, broadband, or DTH bills, manage selected Airtel services, and access financial features such as Airtel Payments Bank and eligible loan or credit services. Available options may vary depending on your country, account, and eligibility.
02Can I recharge mobile numbers and pay bills through the Airtel app?
Yes. The app generally allows users to recharge Airtel prepaid numbers and, in supported regions, other mobile connections as well. It can also provide bill payment options for services such as postpaid mobile plans, broadband, DTH, electricity, water, and other utilities. Before confirming a transaction, carefully check the number, plan, amount, and payment method because completed recharges may not always be reversible.
03Is Airtel Payments Bank safe to use?
Airtel Payments Bank includes features such as account access, money transfers, bill payments, and other banking services, subject to local regulations and account availability. Security can include mobile-number verification, PINs, passwords, and one-time passwords. Never share your OTP, banking PIN, card details, or login credentials with anyone, including people claiming to represent Airtel. Use the official app and keep your device protected.
04Can every user apply for loans through Airtel: Recharge, Bank & Loans?
No. Loan and credit features are normally offered only to users who meet specific eligibility requirements determined by Airtel or its partnered financial institutions. Approval may depend on factors such as identity verification, account history, income information, credit records, and local regulations. The app may display an offer without guaranteeing approval, so review the lender’s interest rate, fees, repayment schedule, and terms before accepting.
05Are there fees for using Airtel’s recharge, banking, or loan services?
Some basic app functions may be free, but certain transactions can involve service charges, convenience fees, taxes, withdrawal costs, transfer fees, or other applicable charges. Loan products may also include interest, processing fees, late-payment penalties, or additional costs. Always read the final payment summary and the complete loan agreement before confirming. Fees and available services can differ by location, account type, and current Airtel policies.


